Monetization Models for Independent Record Labels
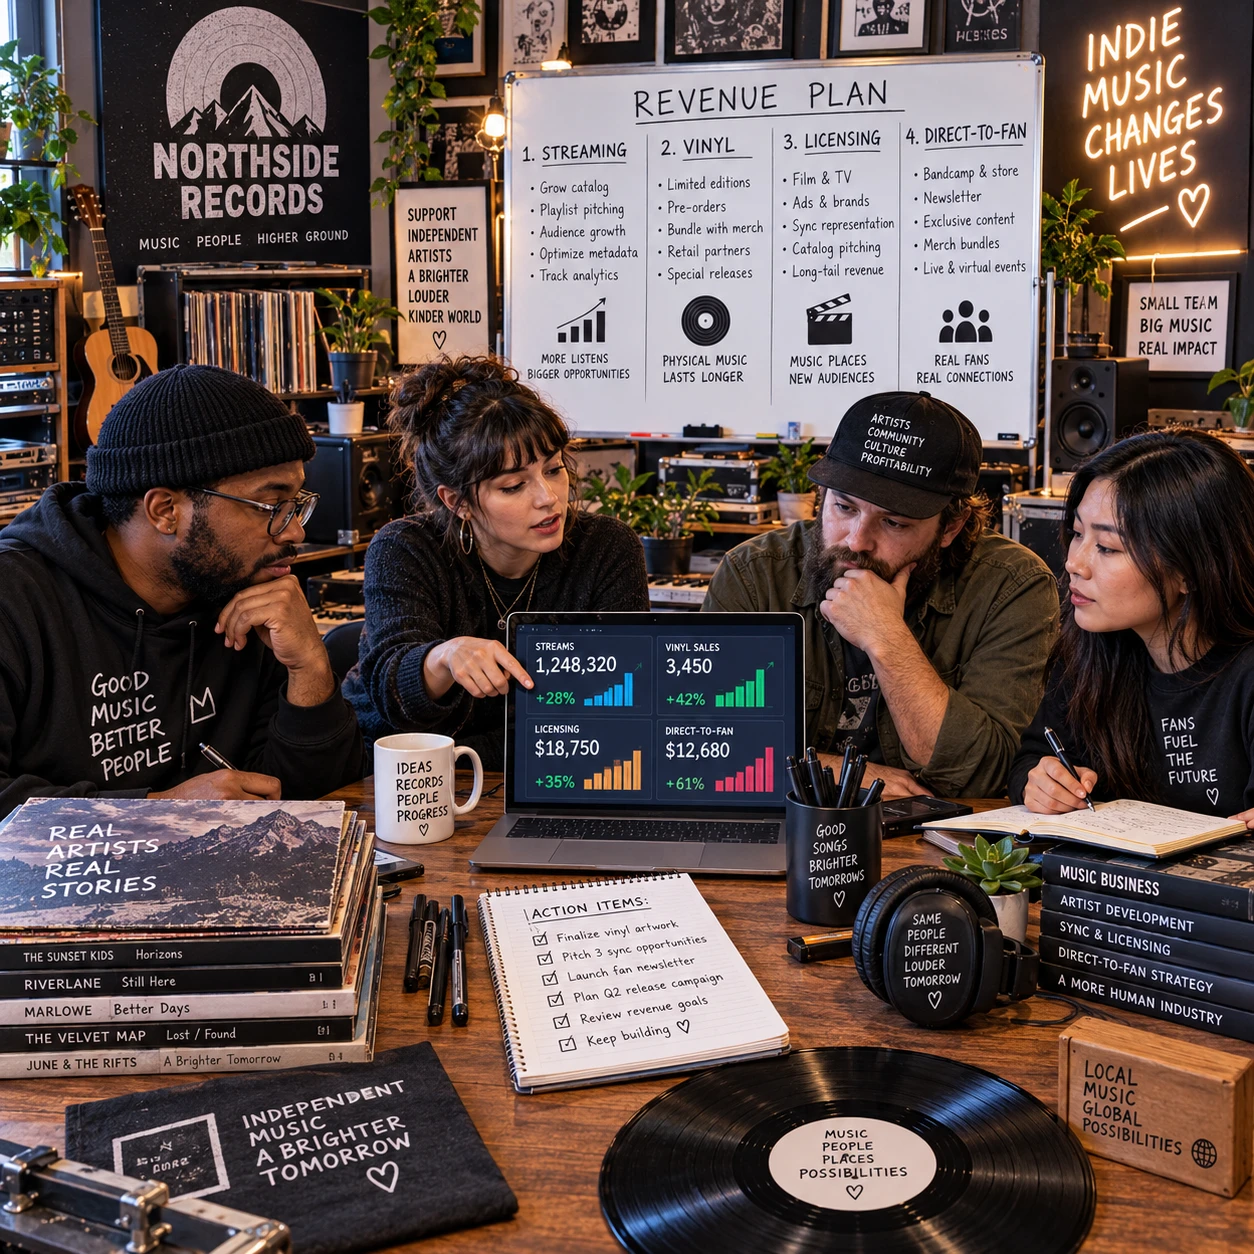
Independent record labels rarely rely on one dependable source of income. Streaming, physical releases, licensing, merchandise, and direct-to-fan sales can all contribute, but each depends on different rights, audiences, costs, and agreements. The first step is to distinguish money earned by the label from income belonging to an artist or songwriter.
How Independent Labels Generate Revenue
Independent labels generate revenue by exploiting the rights and products covered by their agreements, including master recordings, physical releases, licensing, and sometimes merchandise. Which party receives each payment depends on ownership, administration, and the artist’s contract.
A useful way to track income is to ask three questions: what is being sold or licensed, who controls the right, and what costs or splits apply? A label that owns or licenses a master recording may receive recording income from a distributor. The artist’s share is then calculated under their agreement. Songwriters and publishers may receive separate publishing royalties for the composition.
Common label revenue sources include:
- Recorded music: streaming royalties, downloads, and physical sales tied to master recordings.
- Licensing: fees or royalties from uses such as film, television, advertising, and games.
- Physical and fan commerce: vinyl, CDs, special editions, bundles, and direct-to-fan sales.
- Additional activity: merchandise or live-related income when the label has a clear role and agreement.
These figures are not interchangeable with an artist’s personal income. A label may collect a payment and owe part of it to the artist, while publishing income may flow to songwriters or publishers through separate arrangements. Gross receipts also differ from profit: manufacturing, marketing, distribution, and other agreed costs can reduce what remains.
Streaming and Digital Distribution
Streaming royalties reach an independent label through a digital distributor or another rights administrator, then flow according to the label’s ownership and artist agreements. A distributor delivers music and reports platform earnings; it does not automatically determine who owns the masters.
The basic chain is straightforward: the label or rights holder delivers a release to a digital distributor, the distributor supplies services such as Spotify and Apple Music, and those platforms report and pay for usage under their arrangements. The distributor may charge a fee, retain a percentage, or collect a subscription. The label then accounts to the artist based on the contract.
Per-stream earnings are not a fixed rate. They can vary with platform, territory, subscription and advertising revenue, listener activity, and the platform’s payment model. That makes streaming useful for reaching a broad audience and building catalogue discovery, but hard to forecast as a standalone business plan.
Before choosing digital distribution, compare fees, payment schedules, reporting detail, takedown procedures, and support for multiple rights holders. Keep statements and release metadata organized so the label can match receipts to tracks, territories, and contractual splits. If the label does not own a master, its ability to collect or direct recording revenue depends on its license and administration terms.
Physical Sales and Direct-to-Fan Income
Physical sales and direct-to-fan income come from selling formats such as vinyl and CDs, often through a label store, at shows, or in limited bundles. They can produce more revenue per purchase than a stream, but require upfront spending and careful inventory planning.
Vinyl can make sense for an artist with a committed audience, a strong visual identity, or a release that lends itself to a collectible edition. CDs may offer a lower-cost format for some audiences and genres. In both cases, calculate the full unit economics before placing an order: manufacturing, freight, packaging, payment processing, storage, fulfillment, taxes, and returns all affect the margin.
Direct-to-fan sales give labels more control over presentation and customer relationships than marketplace-only sales. A store can offer signed records, bundles with shirts, or a pre-order that helps estimate demand. The trade-off is operational work: the label must manage fulfillment, customer service, and accurate delivery estimates.
Use a small test rather than treating a large pressing as proof of confidence. For example, open a pre-order window, set a production threshold that covers costs, and communicate clearly if manufacturing delays occur. Pre-orders can reduce inventory risk, though they do not remove the need to fund production or meet delivery obligations.
Licensing, Publishing, and Catalogue Value
Sync licensing allows music to be used with visual media, while publishing royalties relate to the underlying song composition. A recording and its composition are separate assets, so a production may need permission from both the master owner and the relevant songwriter or publisher.
The master recording is a specific recorded performance. The composition is the underlying music and lyrics. A label that controls the master may negotiate a master-use license for a film, TV show, advertisement, or game. The song’s publisher, administrator, or songwriter handles the composition-side permission and related publishing income. If one company controls both sides, it may be able to clear them together, but the rights still remain distinct.
Sync work may involve an upfront fee, performance royalties where applicable, or both, depending on the use and agreements. Placements are competitive and unpredictable, so labels should keep metadata accurate, document ownership and splits, and prepare clean versions or instrumental mixes when appropriate. A music supervisor cannot efficiently consider a track if clearance contacts and rights information are unclear.
A catalogue can gain value when recordings continue to attract listeners or remain suitable for licensing. That potential depends on demand, rights duration, ownership, and the quality of revenue records. Catalogue value is not a guaranteed asset price; weak documentation or unclear splits can complicate licensing and future transactions.
Revenue Sharing and Artist Agreements
Revenue sharing and artist agreements determine how label income is divided, which costs can be recouped, and who controls the masters. Clear written terms matter because a headline royalty percentage alone does not explain the full economics.
An artist advance is usually an upfront payment made under the agreement, not automatically a bonus that the label can reclaim from the artist personally. Many contracts recoup the advance from the artist’s share of defined future earnings, but the treatment varies. Recording, video, marketing, and other costs may also be recoupable if the contract says so and defines how accounting works.
For example, if a label pays an advance and funds a recording, the agreement may allow specified costs to be recouped from the artist’s royalty account before additional royalties are paid. The label’s cash flow is still exposed: if the release earns too little, those costs may never be recovered. A higher artist royalty can be fair, but it may leave less room for the label to finance promotion or future releases.
Review agreements for:
- Ownership or license of master recordings, including term and territory.
- The revenue base and percentage used for artist royalty calculations.
- Which advances and expenses are recoupable, and whether recoupment is release-by-release or cross-collateralized.
- Accounting frequency, audit rights, payment thresholds, and deductions.
- Who controls sync approvals, physical sales, and other licensing decisions.
Labels and artists should have an entertainment attorney review terms before signing. Transparent statements and consistent reporting help prevent a revenue-sharing arrangement from becoming a dispute.
Building a Sustainable Mix of Revenue
A sustainable revenue mix matches income streams to the label’s roster, audience, rights, and operating capacity. Start with the assets and demand already in hand, then test additional models without assuming every release needs every revenue channel.
Use a simple rights, audience, capacity check. First, identify the rights the label can actually monetize. Next, look at how fans engage: streaming listeners may not be physical buyers, while a smaller, dedicated audience may respond well to vinyl or direct-to-fan bundles. Finally, assess the labor and cash each channel requires. A label with limited working capital may prefer digital distribution and targeted pre-orders over holding large inventories.
Build a release-level forecast with conservative assumptions. Track expected receipts, manufacturing and marketing costs, payment timing, artist shares, and recoupment separately. Review actual results after each release; compare not only gross income but also net contribution and time spent. A channel that sells well but consumes substantial staff time may not be the right next step for a small team.
Streaming can support discovery, physical editions can deepen fan engagement, and sync licensing can add value when rights are clear. Merchandise and live activity may complement these streams when the label has an agreed role, but they should not be counted as label income by default. The strongest plan is a portfolio of compatible models, with room to change when audience behavior or costs change.
Frequently Asked Questions
Independent label income depends on rights, distribution, and artist agreements, so the same revenue stream can be split differently from one label to another. These answers clarify the most common distinctions.
How do independent record labels make money?
They may earn from master recording revenue, physical and digital sales, sync licensing, and other contracted activity such as merchandise. The label’s share depends on ownership, licenses, costs, and revenue-sharing terms.
Do labels earn royalties from streaming?
Yes, when a label owns or administers the relevant master rights, it can receive recording income through a distributor or rights administrator. Its agreement with the artist determines how that income is accounted for and shared.
What is the difference between master and publishing royalties?
Master income relates to a particular sound recording. Publishing royalties relate to the underlying composition, including its music and lyrics, and are paid to songwriters or their publishers or administrators under applicable arrangements.
How do advances and recoupment affect label income?
An advance is an upfront payment governed by the artist agreement. If it is recoupable, the label may recover it from specified future royalties before further payments are due, but the label risks not earning enough revenue to recoup its outlay.